The Difficulty of Saving for College

The Difficulty of Saving for College

Over the past 18 years, the price of college has increased by 125%, or 4.6% per year (source). This is more than twice as high as the overall inflation rate.

With college costs increasing rapidly, parents who want to save for their children’s education are in a tough situation. If the price continues to increase at that rate, a school that costs $50,000 today will cost $112,000 per year in 2039. This means you would need approximately $448,000 to cover four years of college.

To save that much you would need to put away $1,250 per month, or $15,000 per year, for 18 years assuming a 5% rate of return. Most parents cannot afford to save that much, especially with multiple children.

This also assumes the child finishes their undergraduate degree in four years, which only 41% of students do (source). This also does not account for the cost of a postgraduate degree.

As a financial planning professional, college funding is a struggle. While a 529 college savings account is an excellent place to save, the potential costs are exorbitant.

Assumptions have to be made when saving for a goal, but the variability in those can be massive. What remains unclear is:

  • What will college look like in the next 10-20 years? Perhaps it will look similar to today but the price inflation will decrease.
  • Or, will lower-priced credential options arrive? Companies like Treehouse are interesting early entrants.
  • Will community college be free? The Biden administration is making a push for this to happen.
  • Will my child receive a scholarship or student aid?
  • Another interesting and evolving area is how to borrow for college. One new idea is income-share agreements.

Within this changing landscape, “save what you can and watch what happens” is not the most reassuring financial advice. But as with all financial planning problems, the future is unknowable and we have to accept reality on reality’s terms.

Parents should address their specific college saving goals with an advisor and revisit those assumptions and variables regularly.

Subscribe

Join Our Newsletter

Sign up to receive an email when new articles are posted.
The information, analysis, and opinions expressed herein are for general and educational purposes only. Nothing contained in this commentary is intended to constitute legal, tax, accounting, securities, or investment advice, nor an opinion regarding the appropriateness of any investment, nor a solicitation of any type. The material has been gathered from sources believed to be reliable, however Think Different Financial Planning cannot guarantee the accuracy or completeness of such information, and certain information presented here may have been condensed or summarized from its original source. All opinions and views constitute our judgments as of the date of writing and are subject to change at any time without notice.
Weekly Newsletter: The 3-1-1

Weekly Newsletter: The 3-1-1

I hope you’re doing well and having a great week.

Please see this week’s articles, chart, and quote below, along with an article I wrote about my lesson from investing in gold.

3 Articles

One Year Since the COVID Crash: How Far We’ve Come
YCharts

YCharts did a great visual summary of the past year, showing the impact of COVID-19 on the market and our lives.

Preview of Joe Biden’s “American Families Plan” Tax Reform
Mitchell Baldridge, Twitter

More details are coming out about the American Families Plan tax reform. The proposed changes will impact individuals (capital gains and ordinary income tax rates), corporations, estate, gift tax, and international taxes.

The Growth-Value Cycle
Ben Carlson, A Wealth of Common Sense

For the past decade, growth-oriented stocks, such as technology companies, provided great returns. In the first quarter of 2021, value-oriented stocks, their counterpart, outperformed. This article describes the cyclical nature of these two investing styles.

1 Chart

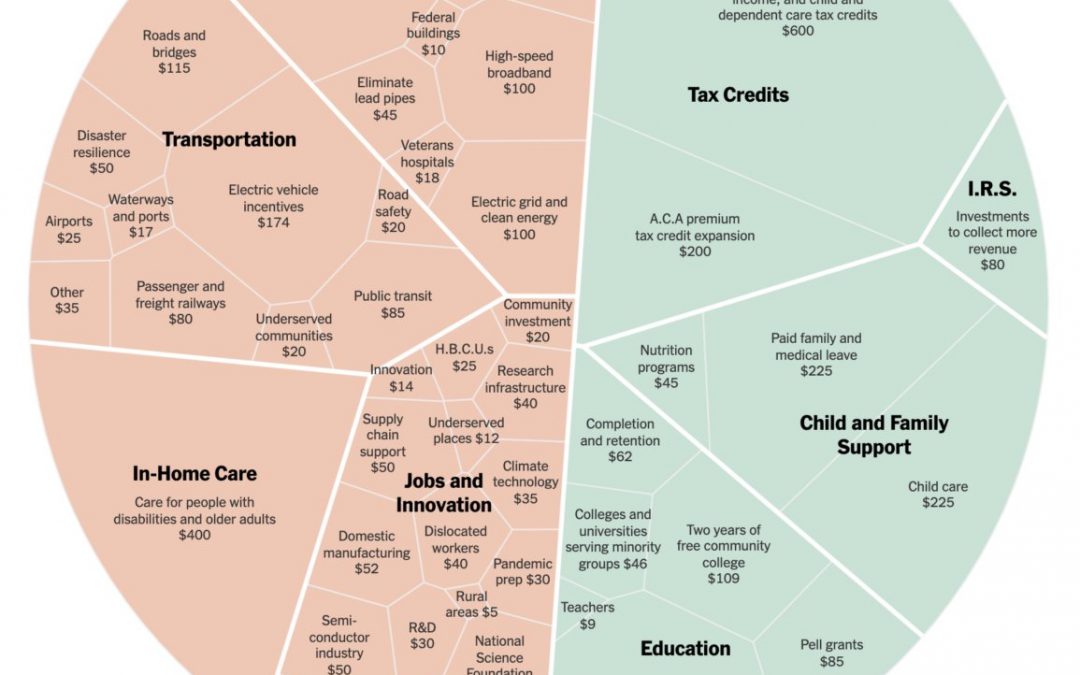
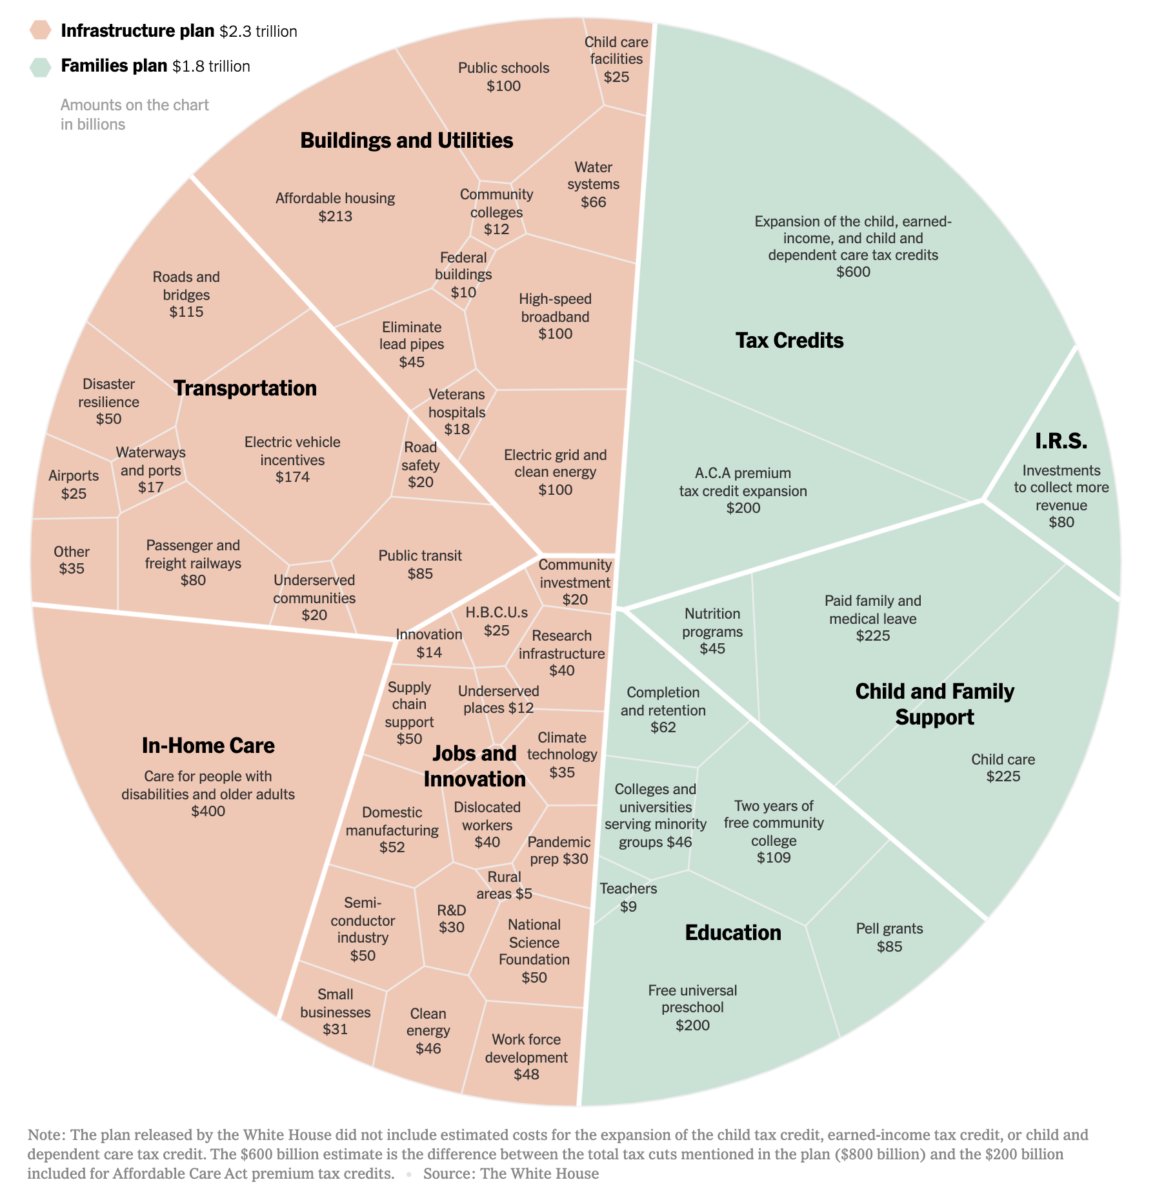
Biden’s $4 Trillion Economic Plan in one chart:

    1 Quote

    “Being afraid to lose money will keep you from making it.”

    – Anonymous

      Written by Will This Week

      My Lesson From Being A Gold Bug
      Around 2010 I was sure gold was a great investment. While that didn’t pan out, the experience was valuable as I learned an important investing lesson.

        Subscribe

        Join Our Newsletter

        Sign up to receive an email when new articles are posted.
        Disclosure: The information being provided is strictly as a courtesy/convenience. When you link to any of the web sites provided here, you are leaving this website. We make no representation as to the completeness or accuracy of information provided at these websites.
        Think Different Financial Planning is not liable for any direct or indirect technical or system issues or any consequences arising out of your access to or your use of third-party technology, web sites, information and programs made available through this website.
        When you access one of these web sites, you are leaving this web site and assume total responsibility and risk for use of the web sites you are visiting.
        Think Different Financial Planning does not make any representations or warranties as to the accuracy, timeliness, suitability, completeness, or relevance of any information prepared by any unaffiliated third party, whether linked to Think Different Financial Planning’s web site or incorporated herein, and takes no responsibility thereof.
        My Lesson From Being A Gold Bug

        My Lesson From Being A Gold Bug

        Around 2010, I was sure gold was a great investment. I was convinced by two “gold bugs,” or fans of gold investing, Peter Schiff and Chris Martenson.

        At the time, they convinced me that the US economy was on the edge of collapse. And when that collapse occurred, owning gold would be the surest way to increase my wealth.

        As you know, that collapse never happened.

        Looking back, I accepted their reasoning and investment recommendation without question. I did none of the following:

        • Analyze the historical returns and characteristics of gold.
        • Think about the opportunity cost of holding it as my largest investment (as compared to other investment options).
        • Think about how much of my portfolio it should comprise. Instead, I went nearly all in.

        I didn’t have one “aha” moment where I changed my mind on investing in gold, but over time the repeated excuses, missed predictions, and continued rationalizations wore off. I eventually sold my position and was lucky to come out with only a minor loss.

        What I learned from this experience relates back to “asset allocation.” That simply means how much you own of each investment.

        While you can debate whether gold is good or bad (plenty of people argue each side well), you should never be so sure of your investment idea/strategy/allocation that you over-invest in a single area. Even Jim Rickards, another gold bug, suggests a mere 10% allocation.

        Summary
        No matter how excited you are for an investment, make sure that you are not overly concentrated. There’s a saying in the investment world: “If you can make a killing from it, it can also be a portfolio killer.” This doesn’t just apply to gold, but all investments.

        Continually question your investment thesis and check it against the facts. Try to avoid confirmation bias. Seek other points of view. Factor in your excitement level to gauge how much that may be factoring in. These are all much easier said than done, but hopefully my story is instructive as you consider investment options.

        Subscribe

        Join Our Newsletter

        Sign up to receive an email when new articles are posted.
        The information, analysis, and opinions expressed herein are for general and educational purposes only. Nothing contained in this commentary is intended to constitute legal, tax, accounting, securities, or investment advice, nor an opinion regarding the appropriateness of any investment, nor a solicitation of any type. The material has been gathered from sources believed to be reliable, however Think Different Financial Planning cannot guarantee the accuracy or completeness of such information, and certain information presented here may have been condensed or summarized from its original source. All opinions and views constitute our judgments as of the date of writing and are subject to change at any time without notice.
        Weekly Newsletter: The 3-1-1

        Weekly Newsletter: The 3-1-1

        I hope you’re doing well and having a great week.

        Please see this week’s articles, chart, and quote below, along with a link to my first quarter, 2021, investment commentary.

        3 Articles

        The Craziest Market I’ve Ever Seen
        Nick Maggiulli, Of Dollars and Data

        The joke as investment idea has arrived.

        Timeless Lessons From My Decades in Finance
        David Booth, Dimensional Fund Advisors

        Billionaire David Booth reflects on what he has learned and what he wishes every investor knew.

        How the Pandemic Did, and Didn’t, Change Where Americans Move
        Jed Kolko, Emily Badger, and Quoctrung Bui, The Upshot (The New York Times)

        Migration patterns during the pandemic have looked a lot like migration patterns before it. Some smaller regional metro areas and vacation hubs benefited. But in general, areas that were already attracting new residents kept attracting them. Those that were losing migrants lost more. 

        1 Chart

        Mortgage rates bottomed at 2.65% in January and have been moving higher since.

          1 Quote

          “Money is like manure; it’s not worth a thing unless it’s spread around encouraging young things to grow.”

          – Thornton Wilder 

            Written by Will This Week

            First Quarter, 2021, Investment Commentary
            Further economic stimulus, continued vaccination progress, and overall positive sentiment contributed to a positive start to the year.

              Subscribe

              Join Our Newsletter

              Sign up to receive an email when new articles are posted.

              Disclosure: The information being provided is strictly as a courtesy/convenience. When you link to any of the web sites provided here, you are leaving this website. We make no representation as to the completeness or accuracy of information provided at these websites.
              Think Different Financial Planning is not liable for any direct or indirect technical or system issues or any consequences arising out of your access to or your use of third-party technology, web sites, information and programs made available through this website.
              When you access one of these web sites, you are leaving this web site and assume total responsibility and risk for use of the web sites you are visiting.
              Think Different Financial Planning does not make any representations or warranties as to the accuracy, timeliness, suitability, completeness, or relevance of any information prepared by any unaffiliated third party, whether linked to Think Different Financial Planning’s web site or incorporated herein, and takes no responsibility thereof.
              Investment Commentary – First Quarter, 2021

              Investment Commentary – First Quarter, 2021

              Highlights

              Further economic stimulus, continued vaccination progress, and overall positive sentiment contributed to a positive start to the year for stocks. Passage of the $1.9 trillion stimulus package and potential for significant infrastructure spending in the United States were certainly viewed in a positive light by investors. Vaccine deployment across the world ramped up quickly through the quarter, rising to an average of over 3 million doses being administered in the US per day and over 15 million doses per day globally.

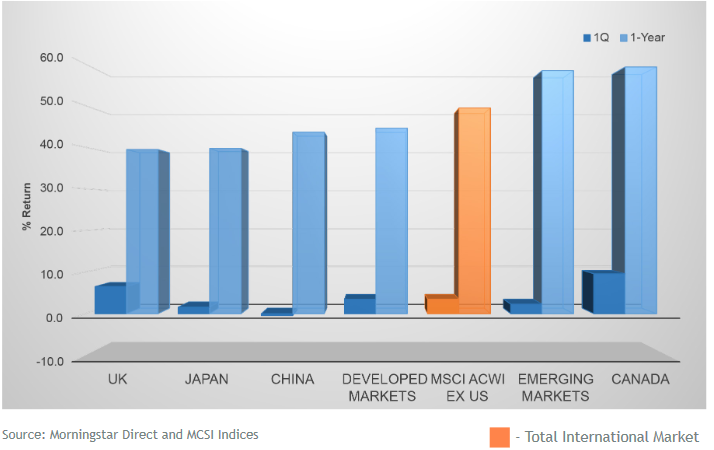
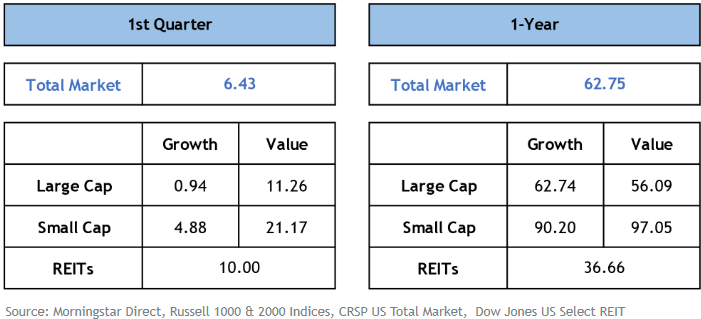
              In the equity markets the US generated the strongest gains with small capitalization stocks leading. International developed and emerging markets also posted positive gains, while modestly trailing US markets. As we look back over the past 12 months, the gains experienced are significant with many markets up over 50% and small cap value in the US up over 100% from the lows seen last March. While informative to see how strongly the markets have rebounded, it is important to keep perspective and remember these are measured from the lows and even just extending the time period to 13 months would meaningfully change the numbers.

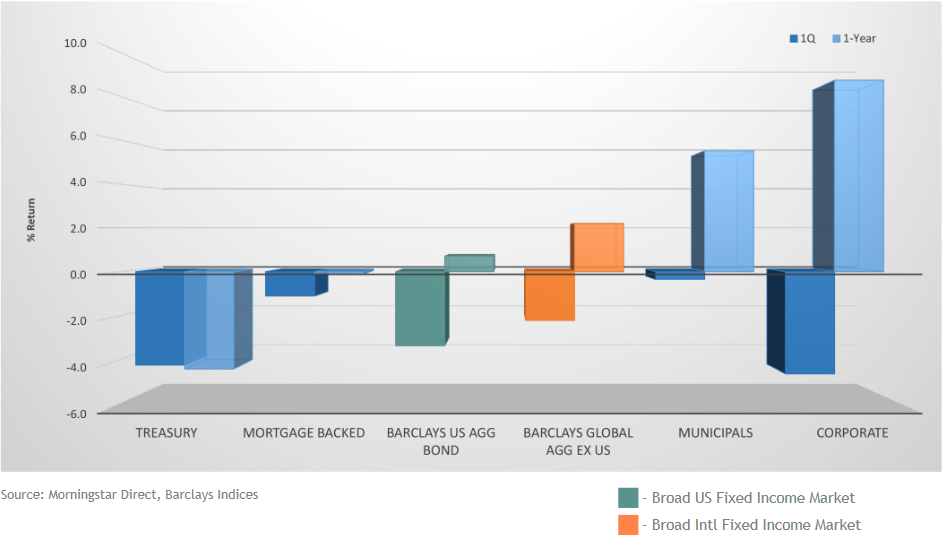
              Within fixed income, short-term interest rates remain near zero, with continued accommodative positions by the Federal Reserve and other global central banks. While the Federal Reserve indicates they remain committed to keeping short-term rates low, the overall direction of the markets and the economy has led to interest rates on intermediate and longer-term bonds moving up during the quarter, weighing on results for fixed income.

              US Stocks

              Stocks in the US gained 6.43% during the quarter and are up 62.75% over the last year. Over the past several years, there has been a wide divergence among equity styles, led by larger growth-oriented stocks. In the fourth quarter of last year, value and smaller-cap names began leading and continued their outperformance through the first quarter. After underperforming the broad market in 2020, REITs rebounded in the first quarter.

              International Stocks

              International stocks also gained during the quarter, appreciating 3.5% and 2.5% for developed and emerging markets, respectively. Again, one-year returns have meaningfully exceeded virtually everyone’s expectations as investors look forward to the opportunities beyond the current situation. 

              Bonds

              Returns within fixed income were generally down during the quarter as interest rates rose. Perhaps unsurprisingly, after performing very well during the flight to quality last March, Treasuries have been the weakest area over the last year. Hedged international bonds have provided diversification and benefit where held in portfolios as global yield curves have not moved in tandem with the US. Municipal bonds performed well on a relative basis and held up better than most taxable sectors during the quarter.

              Parting Thoughts

              The S&P 500 Index is one of the most commonly cited and referenced indexes in the world. It appears on the front page of major news sites, in countless articles, and is a barometer than many use to gauge how the markets are doing. Yet, it is actually a fairly narrow definition of the markets. It represents the (approximately) 500 largest US stocks. Yet the global investable market is comprised of over 10,000 stocks. It includes small, mid, and large cap. It includes both the US and over 40 other developed and emerging markets countries. The global opportunity set also contains thousands of fixed income securities.

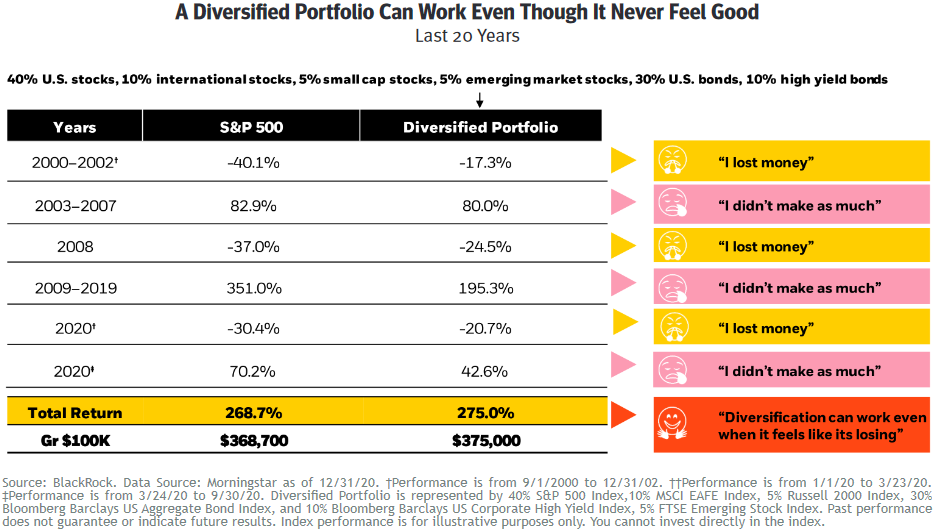
              While most investors understand that their portfolios are structured and managed to their unique goals and objectives, and often bears little resemblance to the composition of the S&P 500, the sheer visibility of the S&P 500 makes it a common point of comparison, even if unintentional. The following chart helps illustrate the limitations that can come from using this as a point of comparison for an investor who holds a diversified portfolio.

              Over the last 20 years, there have been multiple up and down cycles. In down markets, an investor may feel like things are not going well because they are down (even if they haven’t lost as much as the S&P). Research has shown that investors tend to be more sensitive to the pain of losses in portfolios. Then in up markets, they may feel like they are losing out because their portfolio has not gained as much as the S&P. However, as BlackRock points out, even though it may never feel good being in a diversified portfolio, the end result over 20 years was similar but with meaningfully less volatility and risk taken.

              Subscribe

              Join Our Newsletter

              Sign up to receive an email when new articles are posted.
              Disclaimer: The opinions expressed in this article are for general informational purposes only and are not intended to provide specific advice or recommendations for any individual or on any specific security. The material is presented solely for information purposes and has been gathered from sources believed to be reliable, however Think Different Financial Planning cannot guarantee the accuracy or completeness of such information, and certain information presented here may have been condensed or summarized from its original source. Think Different Financial Planning does not provide tax or legal advice, and nothing contained in these materials should be taken as such. As always please remember investing involves risk and possible loss of principal capital. Advisory services are only offered to clients or prospective clients where Think Different Financial Planning and its representatives are properly licensed or exempt from licensure. No advice may be rendered by Think Different Financial Planning unless a client service agreement is in place.