Some Thoughts After a Sad Reminder

Some Thoughts After a Sad Reminder

I normally post a new article around the beginning of each month. In January, I didn’t

The reason is a sad one. Shortly after Christmas, my wife and I learned that one of her best friends suffered a heart attack while out to dinner, went into a coma, and passed away two weeks later.

She was 38 years old. A wife. A healthy mother of two. A successful law firm partner. No known heart issues, no warning signs, just…gone. We’re waiting to see if a rare genetic disorder may have been the cause.

We recently returned from her funeral, where we shared stories and grieved together. Those few days sat under a dark cloud of sadness, especially the receptions that were held in her home, which is filled with pictures of better times, alongside her favorite books and art.

This newsletter is usually pretty cut-and-dry: markets, planning ideas, personal finance. But going through that brought up a few thoughts that felt worth sharing. Death is something most of us don’t think about unless we have to. Here’s what has been on my mind:

1. Randomness runs more of our lives than we’d like to admit.
We mostly believe that life unfolds as a tidy story: Cause followed by effect, effort rewarded by outcome. But the simple fact of when and where we are born affects so much: our opportunities, our friends, even our length of days. Death does not always knock politely or follow rules we can understand.

2. We assume “later” is guaranteed.
Because index funds are passively managed, they typically have much lower fees than actively managed mutual funds.

3. Family and close friends matter most.
Watching my wife and her friends drop everything to support each other, travel, and even plan parts of the funeral, was a powerful reminder that relationships are what truly matters.

4. Insurance and estate planning is boring until you need it.
You hope to not even need them. But I’ve seen people pass away without the proper coverage or documentation, and it can make a bad situation much worse.

I’ll be back to more typical market coverage next month, but I wanted to acknowledge the human side of all this while it’s still fresh.

Thanks for reading, and hug your friends/family a little tighter than usual.

Quote of the Month

“Success is being excited to go to work and being excited to come home.”

– Will Ahmed
Follow Up to Thoughts on the “AI Bubble”

Follow Up to Thoughts on the “AI Bubble”

I hope you had a great Thanksgiving.
In the spirit of giving thanks, it’s worth pausing to acknowledge how strong stock market returns have been recently and over the past few years.
But it’s also important to remember that it’s not always this good. Returns will likely settle back toward normal levels, and that adjustment can sting.
For context: Over the last fifteen years, U.S. stocks have returned 18.74% per year, compared with a long-term historical average of 9.94%. That gap won’t last forever.
I’m not calling a top or pretending to know what comes next. But history teaches us that while markets reward long-term investors, the short term is unpredictable, and mean reversion is a real force.
This isn’t a moment for panic or celebration, it’s a reminder to stay grounded, stick to a well-reasoned investment and financial plan, and recognize that this is exactly how markets work. Sometimes they feel effortless, sometimes they’re frightening.
Following up on last month’s newsletter, Thoughts on the AI Bubble, today we look at the stock market from a few different angles. Simply put, the U.S. market is richly priced. But on the other hand, today’s companies are better than anything we’ve seen before, so I show why these high valuations could be justified. As with most things of high quality, they’re not cheap.

Thanks for reading.

Investing / Stock Market
  • 📊 What to Do When the Entire Market Looks Expensive –  “NYU professor Aswath Damodaran [someone I respect and trust]…said that for the first time ever, he’s thinking about moving [some of] his money into cash and collectibles — saying there’s no place to hide in the stock market.
  • He’s not alone. Goldman Sachs strategists predicted last week that U.S. equities will likely underperform global peers for the next decade. They recommended that investors ‘Diversify beyond the U.S., with a tilt toward emerging markets.’
  • The S&P 500’s forward P/E [price-to-earnings] ratio is 22x, above its historical average of 17x.
  • The index has traded above 22x only twice since 1985: during the dot-com bubble and the COVID-19 pandemic. The market fell sharply both times.”
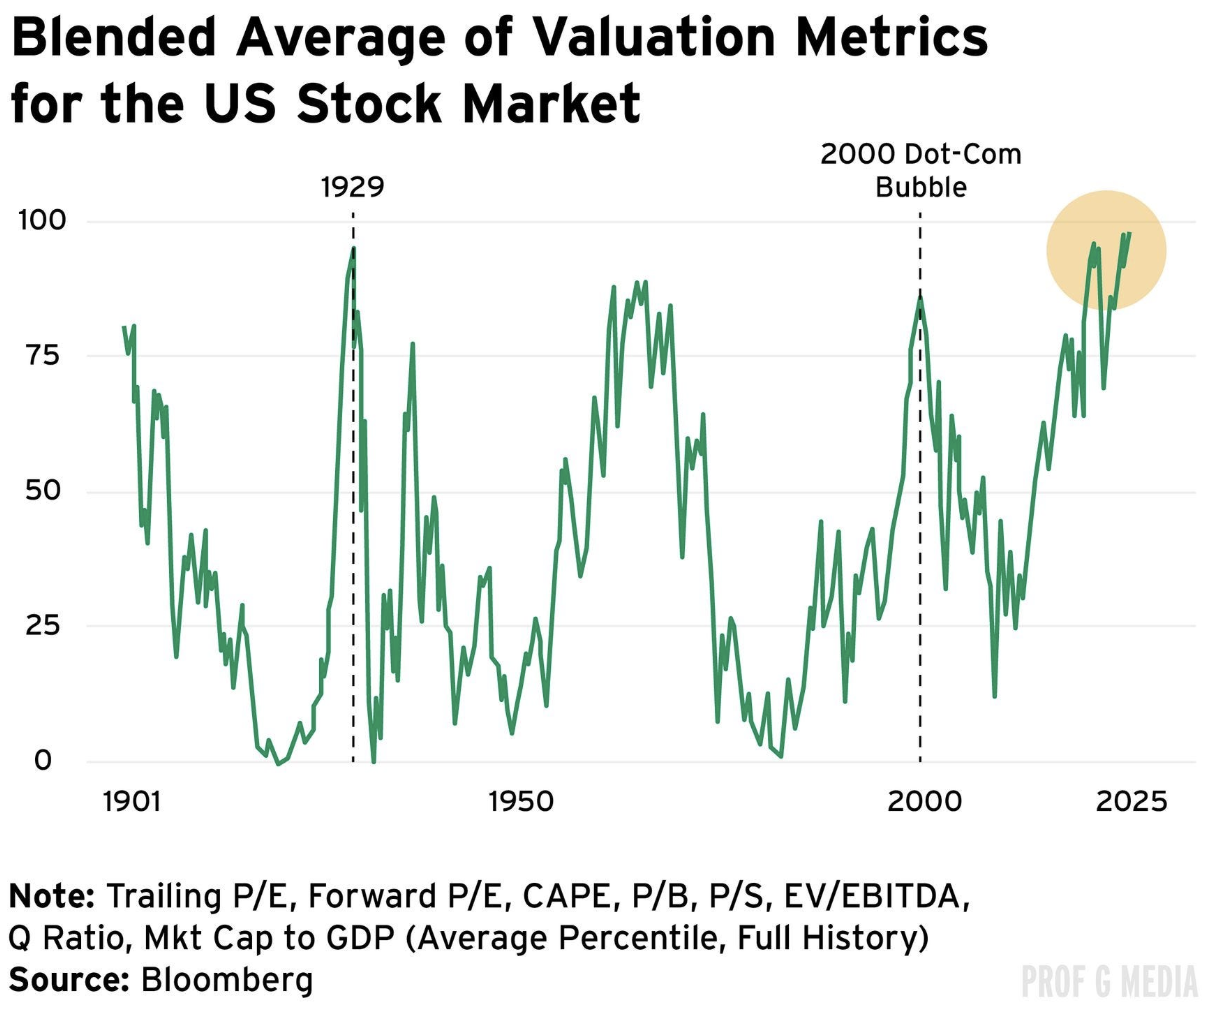
  • Below is blended measure of stock market valuations. Across essentially every metric the U.S. market is expensive. That doesn’t mean it can’t or won’t go higher. It’s just that, expensive.
  • So What?
  • If you’re concerned that the U.S. stock market is overvalued, here are your options:

1. Do Nothing. As long as you have an investment plan in place that suits your risk profile and time horizon, the best move might be to just follow your plan.

2. Hold or build cash.Keep your allocation largely the same but directnewcontributions, or perhaps proceeds from overpriced or concentrated assets, into cash.

3. Change your asset allocation/diversify. Adjust your stock/bond mix, increasing exposure to what you believe is undervalued and reducing what you see as overpriced.

  • Within stocks, diversify globally: Roughly one-third internationally is a good starting point.

4. Buy protection. Use derivatives like puts or futures to hedge your portfolio without altering your core holdings.

5. Make leveraged bets. Take aggressive, leveraged positions, such as buying puts or shorting stocks, to profit from a potential market correction.

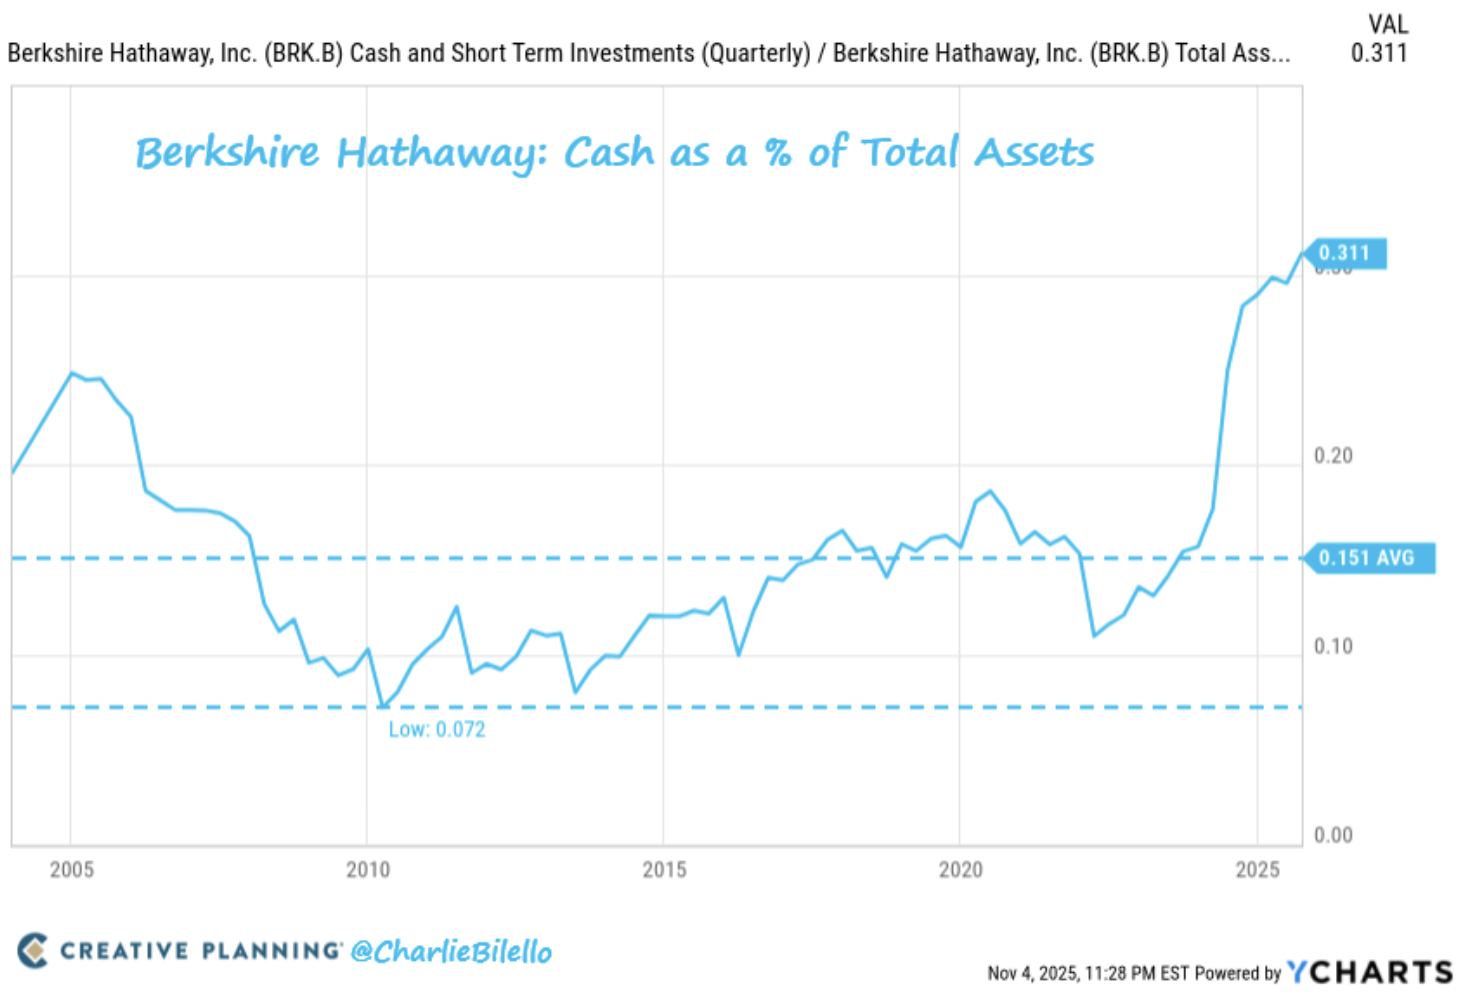
  • Warren said this recently about this topic:
  • “We’d love to spend it [cash]…It’s just that things aren’t attractive.” For now, it seems, Berkshire is positioned very defensively.
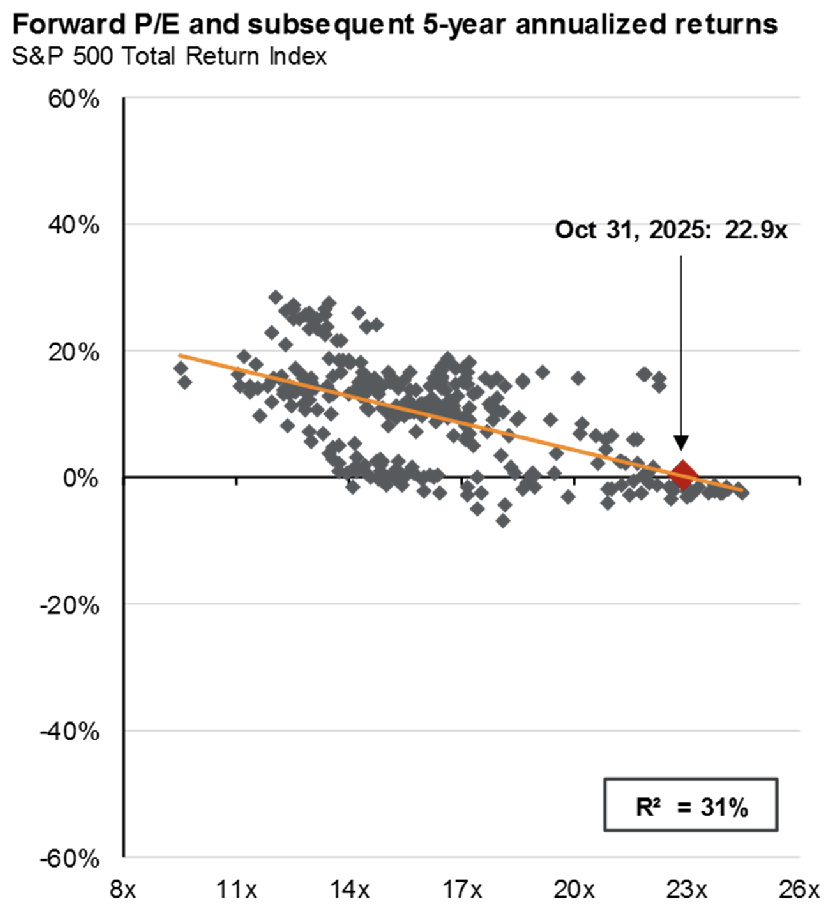
  • Valuations vs. Returns – Stock market valuations, shown on the x-axis below, have historically offered reasonable insight into five-year returns.
  • While it’s a relatively small sample size, if that pattern holds, U.S. market returns over the next five years could be flat or even negative.
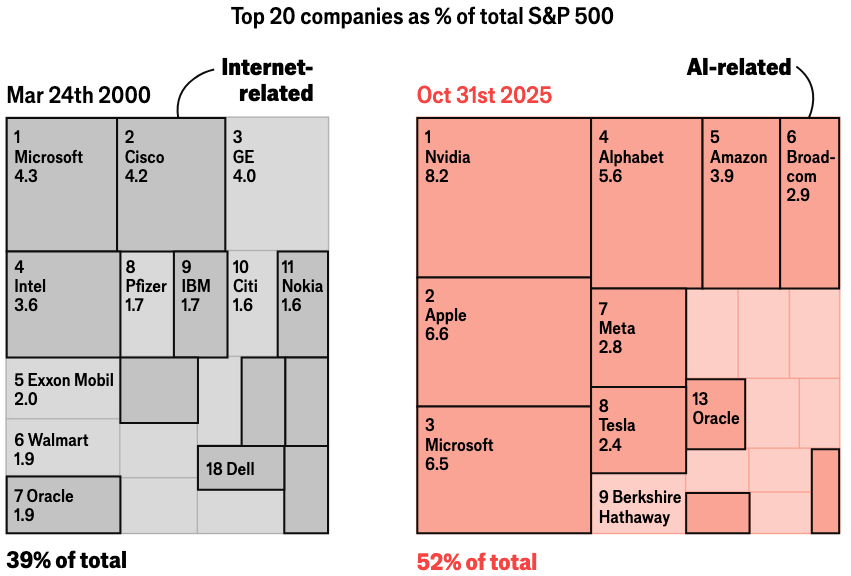
  • AI is Huge – “In 2000 the 20 biggest firms on the S&P 500 made up 39% of its total value. Eleven of those were internet-related companies.
  • Today the top 20 account for 52%, with the same number deeply invested in AI.
  • If the tech fails to deliver juicy returns they would all be hit hard.” — The Economist
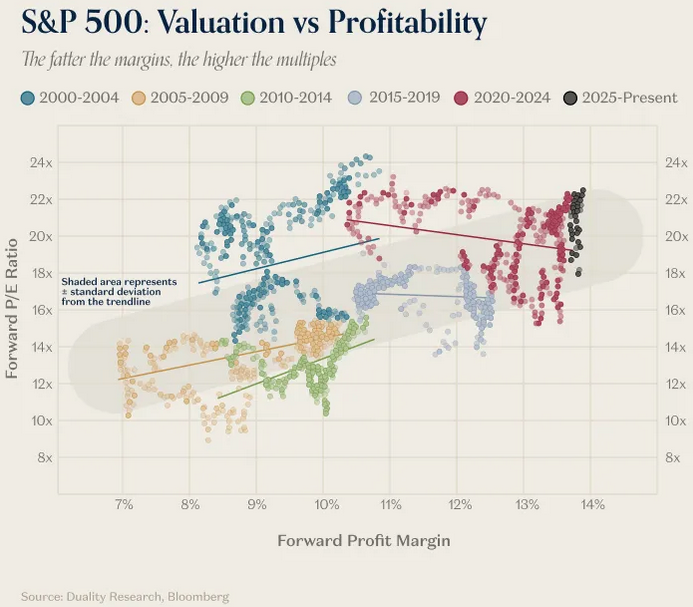
  • “It’s true that multiples on earnings are historically high, but it’s also true that companies are historically profitable–and valuations have scaled accordingly.
  • The point here is that for all the histrionics, investors aren’t dumb. There’s a clear method to the madness, and it’s all about profitability. Fat margins and growing profits lead to high stock prices, and fat margins and growing profits is exactly what PublicCos keep doing.
  • Now, reasonable minds can disagree about whether forward earnings estimates are correct (and there are of course many other things that affect stock prices), but taking them at face value, there is nothing bubbly at all about current valuations.”
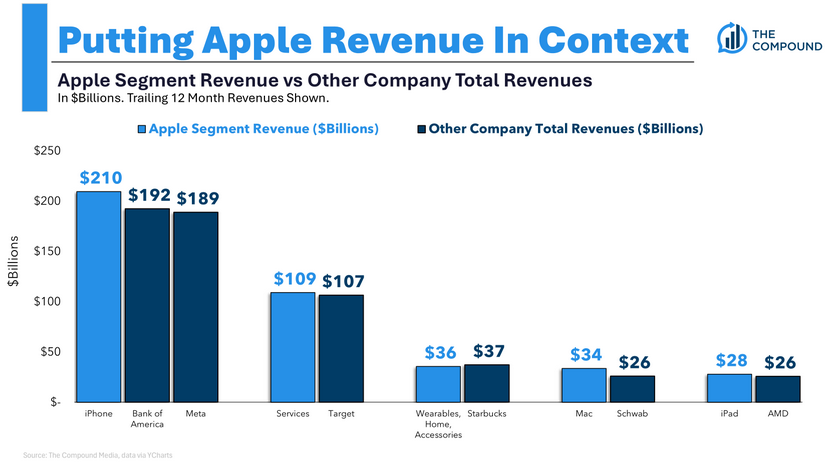
  • 🏦 Record Quarterly Results – Given how profitable today’s companies are, the results and numbers from the following tech companies are extraordinarily impressive.
  • “It was another record quarter for Big Tech, with:
  • Apple revenues growing 8% YoY [year-over-year] to a new Q3 record of $102 billion and net income growing 92% YoY to a new Q3 record of $27 billion.
  • Google revenues growing 16% YoY to a new record high of $102 billion and net income growing 33% YoY to a new record high of $35 billion.
  • Microsoft revenues growing 18% YoY to a new record high of $78 billion and net income growing 12% YoY to a new record high of $28 billion.
  • Amazon revenues growing 13% YoY to a new Q3 record of $180 billion and net income growing 38% YoY to a new record high of $33 billion.”
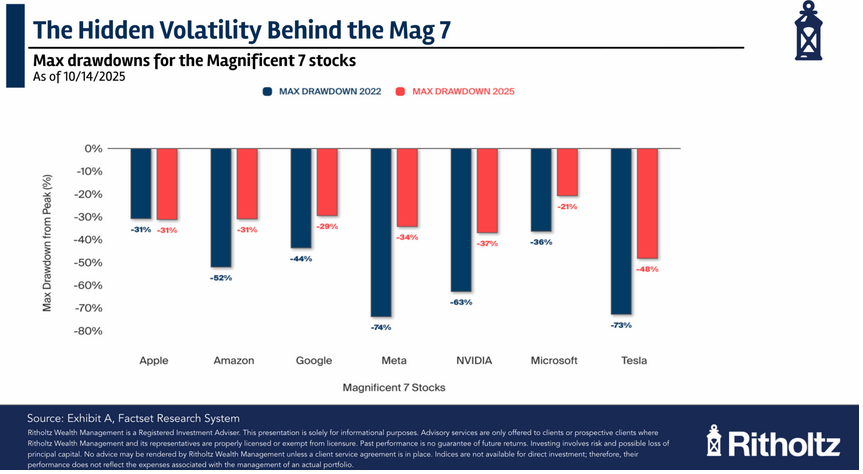
  • Despite these amazing results, the declines (AKA “drawdowns”), whenever they may happen, can be intense:
Quote of the Month

“When people get very excited, as they are today about artificial intelligence, for example…every experiment gets funded, every company gets funded…The good ideas and the bad ideas. And investors have a hard time in the middle of this excitement, distinguishing between the good ideas and bad ideas.”

– Jeff Bezos

I hope you found these interesting.

As always, please reach out if you have any questions or would like to connect.

Thoughts on the “AI Bubble”

Thoughts on the “AI Bubble”

Lately, many financial commentators are bringing up the topic of an “AI Bubble.” 

Andrew Ross Sorkin had this to say (emphasis mine):

“Are we in an A.I. bubble? I’ve heard that question multiple times in one day.

The answer is that we are — we just don’t know when it will end. When the dot-com bubble popped, it wasn’t the end of the internet. It just meant that the weakest companies didn’t survive. And that’s probably what will happen again.”

What we see today are tech companies competing and spending massive amounts on what they believe is needed to build and scale their AI strategy.

Scott Galloway put it well: 

“Big Tech’s business model is flipping from asset-light to asset-heavy. Apple, Amazon, Alphabet, Microsoft, and Meta are on track to spend over $350 billion in capex this year — roughly $100 billion more than last year.

These companies spent the last decade building high-margin, high-free-cash-flow businesses in software, ads, and cloud. Now they’re redeploying those profits into the physical infrastructure of AI…The open question is whether Big Tech’s premium valuations — justified by years of asset-light growth — still hold up as they become asset-heavy.“

From an investment perspective here’s what’s important: You don’t need to time the market to make money and be successful. It reminds me of the following quote from Jack Bogle, the founder of Vanguard:

“The idea that a bell rings to signal when investors should get into or out of the market is simply not credible. After nearly 50 years in this business, I do not know of anybody who has done it successfully and consistently. I don’t even know anybody who knows anybody who has.” 

And remember, stocks don’t need an AI bubble to fall. They can decline for any number of reasons: cycles turn, liquidity tightens, there’s an oil shock, or something else unpredictable happens. The catalyst rarely looks like the one people are talking about ahead of time.

You don’t prepare by predicting the exact cause or moment of a downturn. It’s not possible. You prepare by building a portfolio designed to survive one.

That means diversifying, not just across the big household tech names, but across small, medium, and large companies, across industries, and across the globe.

Above all, know your risk tolerance. Markets have crashed 50% before, and they probably will again someday. The timing and reason is unknowable in advance, but you should have that expectation in mind.

Control what you can, and let markets do what they’ve always done: surprise us in the short run, and reward patience in the long run.

The goal isn’t to call the top. Finding the right portfolio and risk level, and sticking with that through good times and bad, is the best way to sleep well and earn good returns. 

Thanks for reading.

Investing / Stock Market
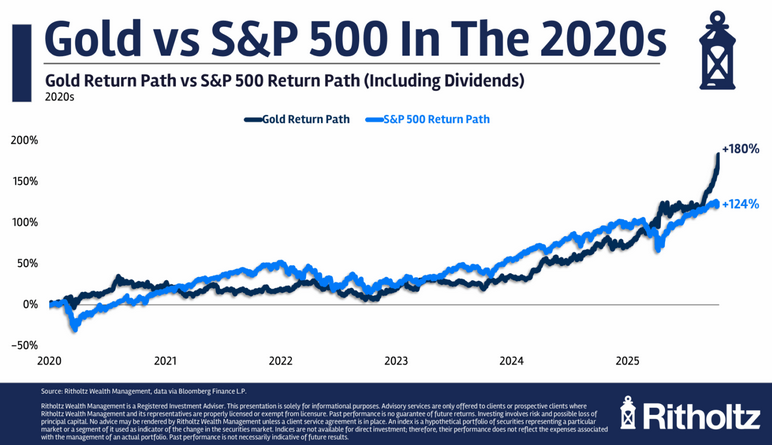
  •  Why I don’t Own Any Gold – “I just don’t have the stomach for an asset that has the ability to experience 3 lost decades out of 4.” — Ben Carlson, Director of Institutional Asset Management, Ritholtz Wealth Management.
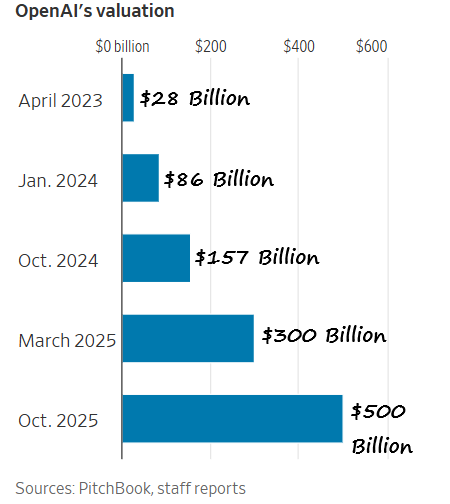
  • 💸 OpenAI’s Value – “If OpenAI was public, it would now be the 16th largest company in the S&P 500.” — Charlie Bilello, Chief Market Strategist, Creative Planning
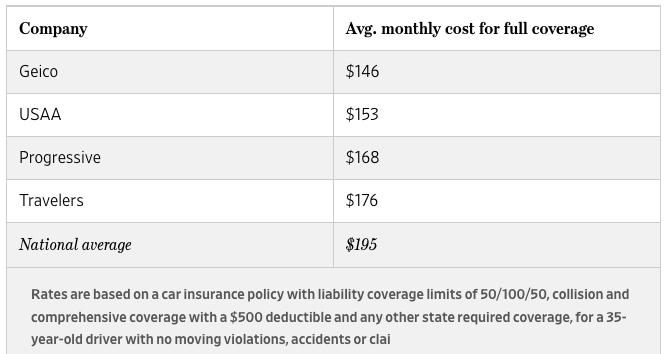
  • Here are the cheapest car insurance companies according to The Wall Street Journal:

Life

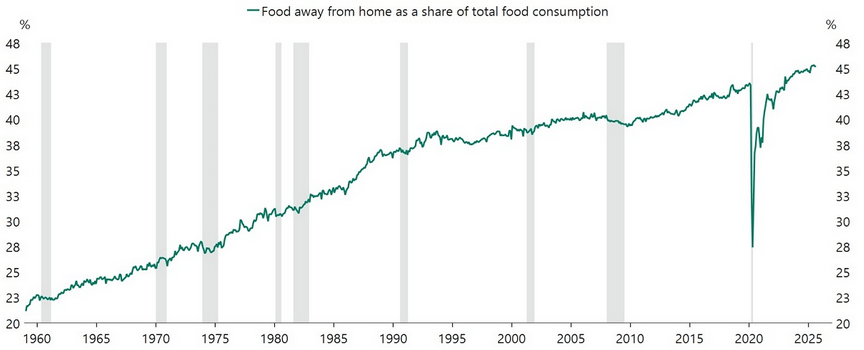
  • 🍔 Food Outside the Home – “Households now spend almost as much on restaurants, takeout and delivery as on groceries eaten at home.”

Quote of the Month

“Pause for a moment and ask yourself, how many of the things you have now are the things that you wished for a decade ago?”

– Trevor Noah

I hope you found these interesting.

As always, please reach out if you have any questions or would like to connect.

Another Strong Quarter

Another Strong Quarter

I hope you had a great Summer and are looking forward to Fall.

The third quarter delivered solid gains: 

  • Stocks rose all three months, and are now up five months in a row. The S&P 500 climbed 7.8% in the quarter.
  • September was unusually calm: Not one day closed up or down more than 1%.

Looking Ahead: October has a reputation for volatility. Some of the market’s largest drops (e.g., 1929, 1987, and 2008) happened this month. After a long stretch of strength this year, a short-term decline wouldn’t be surprising.

The economy remains resilient, despite tariff headwinds:

  • U.S. GDP grew 3.8% in Q2, the fastest pace in nearly two years.
  • Corporate earnings are on track to rise 12% year-over-year, the third straight quarter of double-digit growth.
  • Unemployment sits at 4.3%, well below recessionary levels.
  • Retail sales are still climbing, showing strong consumer spending.

Big Picture Theme: Artificial Intelligence (AI)
AI has become the economic story of the decade. Tech giants are racing to secure the computing power and talent needed to build the most advanced models. Here are a few eye-catching stats (emphasis mine):

  • “AI-related stocks have accounted for 75% of S&P 500 returns, 80% of earnings growth, and 90% of capital spending growth since ChatGPT launched in November 2022.” (JPMorgan)
  • “The AI boom has contributed 40% of [America’s] GDP growth over the past year—a staggering figure for a sector that accounts for just a few percent of total output.” (The Economist)
  • “There are now 498 AI ‘unicorns,’ or private AI companies with valuations of $1 billion or more, with a combined value of $2.7 trillion, according to CB Insights. Fully 100 of them were founded since 2023. There are more than 1,300 AI startups with valuations of over $100 million. (CNBC)

For investors, this underscores the importance of diversification. Chasing hype with concentrated bets can be risky, but ignoring innovation is also a bad idea. Spreading your investments helps ensure you own the eventual winners that rise to the top.

Thanks for reading.
Investing / Stock Market
  • 📈 13 Years of All-Time Highs – “We’ve now seen 13 straight years with at least 1 all-time high, surpassing the epic 1989-2000 streak (12 years).”
  • — Charlie Bilello, Chief Market Strategist, Creative Planning
  • 📊 Sector Performance in 2025 – “Technology and communication services (basically tech) both experienced massive drawdowns earlier this year [down 26.2% and 22.7%] but are now each sitting on 20%+ gains for the year.“
  • — Ben Carlson, Director of Institutional Asset Management, Ritholtz Wealth Management.
  • — Ryan Detrick, Chief Market Strategist, Carson Group
  • 🚀 More IPOs  – “About $7.6 billion worth of I.P.O’s priced in the US in September [Klarna, Netskope, Stubhub, were a few], making it the biggest month for such deals since 2021. — Bloomberg. 
  • The strength seen in September suggests a potential turning point in the IPO market, which has been languishing for some time.
  • 💸 Safe Retirement Withdrawal Rates – In personal finance news, many people are familiar with the concept of the 4% rule. It states that a sustainable withdrawal rate from your portfolio is 4%.
  • For example, if you have one million dollars, you can withdraw $40k per year, and increase that each year for inflation. It’s a simple, back-of-the envelope calculation that ignores taxes, Social Security income, and much more, but it turns out that the “4%” has been revised and increased to 4.7%. 
  • “The chart shows the percentage of retirees that did not run out of money over 30 years based on initial withdrawal rate.
  • As you can see, not a single retiree ran out of money with a 4.68% withdrawal rate (which Bengen rounds to 4.7%):”
  • For retirees, the increase offers a bit more flexibility. But keep in mind that this is a very high-level rule, and personal circumstances still matter.
  • 💸 Forced Roth 401(k) Savings For Those Over 50 – In more personal finance news, employees age 50 and up are allowed to contribute an extra $7,500 per year to their 401(k), on top of the standard $23,500 limit for 2025. This is called a “catch up” contribution.
  • Starting next year, workers age 50+ who earn over $145,000 must make their 401(k) catch-up contributions after tax (within Roth accounts).
  • Also noteworthy: A special “super catch-up” option allows people between 60 and 63 years old to increase their catch-up contribution to $11,250.
Real Estate
  • % Mortgage Rates: The Fed’s recent 0.25% interest-rate cut doesn’t automatically mean mortgage rates will fall much. Mortgage rates depend more on long-term bond markets, inflation expectations, and lender costs. So we could see only a small change, not a big drop.
  • ⏳ Homes Sell At Slowest Pace in a Decade –  “The typical home that went under contract in July was on the market for 43 days. That’s up from 35 days a year earlier and is the longest span for any July since 2015.”
  • — Lily Katz, Data Analyst, Redfin
  • $ Housing Price Declines – In July, “home prices fell in 39 of the 50 most populous U.S. metro areas on a seasonally adjusted basis, month over month…The highest number of metros to post a monthly decline going back to 2012.”

Life

  • Financial Advice for Kids – This is a great letter from Morgan Housel to his son. Written back in 2015, it’s still well worth a read. 
  • 👶 Daycare Costs – San Francisco, San Mateo, and Santa Clara County have some of the most expensive daycares in the country. 

Quote of the Month

“Wealth has an interesting way of distorting our perceptions and changing our motivations. Even people who are objectively successful can be made to feel otherwise.

If you want to counteract these pernicious effects, then you will need to remember who you are and what you value. Finding ways to enjoy your money without identifying with it should be your end goal. That’s how you protect your wealth from yourself.”

– Nick Maggiulli

I hope you found these interesting.

As always, please reach out if you have any questions or would like to connect.

August’s Top Personal Finance News

August’s Top Personal Finance News

I hope you had a great Labor Day weekend.

Here’s how investment markets performed in August:

  • US Stocks. The S&P 500 rose 1.9%, the fourth-straight month of positive returns. Over the past 100 days, the index is up more than 25%. US stocks as a whole (including small- and medium-sized companies) rose 2.5%.
  • International Stocks. International stocks were up 3.3%. 
  • Bonds. US bonds appreciated 0.8%, while international bonds were flat. 

Regarding inflation, The Federal Reserve’s preferred measure came in at 2.9% for July, the latest data available. That is increasing versus the past few months: June (2.8%), May (2.7%), and April (2.6%), and above their 2% target. See the last bullet point below for why tariff-driven inflation hasn’t fully materialized.

In August we also learned of a weakening jobs market: July added just 73k jobs, below the 100k expected. May and June’s job numbers were also revised down by 258k total, leaving the 3-month average at a fairly weak 35k. 

As a result, The Fed seems open to an interest rate cut this month. This has more to do with the weak job market, and less to do with inflation settling down to their 2% target.   

Thanks for reading.  

Investing / Stock Market
  • 🌐 Global Stock Market Performance – “Almost every other country with a decent-sized  economy is outperforming the U.S. stock market in 2025.” — Ben Carlson, Director of Institutional Asset Management, Ritholtz Wealth Management
  • September Clouds? – “September is historically the worst-performing month for the S&P 500…since 1928, the index was down an average of >1%, posting gains only 44% of time” — Liz Ann Sonders, Chief Investment Strategist, Charles Schwab
  • 📈 S&P 500 Up More than 25% in 100 Days – In good news, “The S&P just rallied 25%+ over 100 trading days for the 12th time in the last 70+ years. Three months later, it was higher every time.” — Bespoke Group
Real Estate

A note on the housing market:

“Renting looks superior to buying throughout most of the country. As John Burns Research and Consulting noted in early July, ‘For the first time since 2006, purchasing an entry-level home costs more than twice as much per month as renting.’” — Nick Maggiulli, Of Dollars And Data

As a result, “homebuyers are in the best position in more than five years to find the right home and negotiate for a better price. Current inventory is at its highest since May 2020” — Lawrence Yun, Chief Economist, National Association of Realtors.

  • 🔮 Housing Price Declines Ahead? –  “America’s housing market is flagging. Across the country, prices have drifted down in the first half of the year, with most cities [75%] seeing falls in the past three months.” — The Economist, America’s housing market is shuddering
  • As you can see, the 3-month figure is a leading indicator for the 1-year figure, suggesting that housing-price declines may be ahead:
  • $ Housing Prices, Past Year – “Prices are still creeping up in the north-east and the mid-west, but the west and, in particular, the south are hurting.” — The Economist, America’s housing market is shuddering
  • 🐢 Slow Real Estate Markets – These places are seeing homes sit on the market for much longer compared to a year ago:

Jobs / Tariffs

  • Tough Times for Young Software Developers – “Among software developers aged 22 to 25…head count was nearly 20% lower this July versus its late 2022 peak…daunting obstacles for the large number of students earning bachelor’s degrees in computer science in recent years.” — Justin Lahart, The Wall Street Journal
  • 🌎 Tariffs Delayed Effect – “Barclays research suggests that inflation hasn’t increased that much partly because the U.S. hasn’t collected tariffs on many goods—for now. In June, just 48% of U.S. imports were actually subject to tariffs, thanks to myriad exemptions…
  • Ultimately, however, the actual rates importers pay are likely to rise in months to come, according to Barclays. Many of the existing loopholes could close. Trump has threatened 250% tariffs on pharmaceuticals and 100% tariffs on semiconductors. The White House has also said that as of later this month, it is suspending the de minimis exemption, which allows duty-free shipments to the U.S. as long as they are valued at $800 or less [the de minimis exemption expired August 29th, 2025].
  • Ultimately, Barclays expects weighted-average tariffs to end up at around 15%, up from a current 10% and 2.5% last year…That could mean much of the likely tariff hit is still in the future.” —  Konrad Putzier, The Wall Street Journal

Quote of the Month

[Regarding inheritance]

“Leave the children enough so that they can do anything, but not enough that they can do nothing.”

– Warren Buffett

I hope you found these interesting.

As always, please reach out if you have any questions or would like to connect.